Imagine trying to buy a coffee with a hundred-trillion-dollar note. That’s not a joke from a bad movie; it actually happened in Zimbabwe in 2015 due to hyperinflation. This extreme example highlights the fragility of traditional money and why many people are looking for alternatives. If you’ve ever wondered whether digital currency is truly better than the cash in your wallet, you’re asking the right question. The debate isn't just about technology; it's about trust, control, and how value moves around the world.
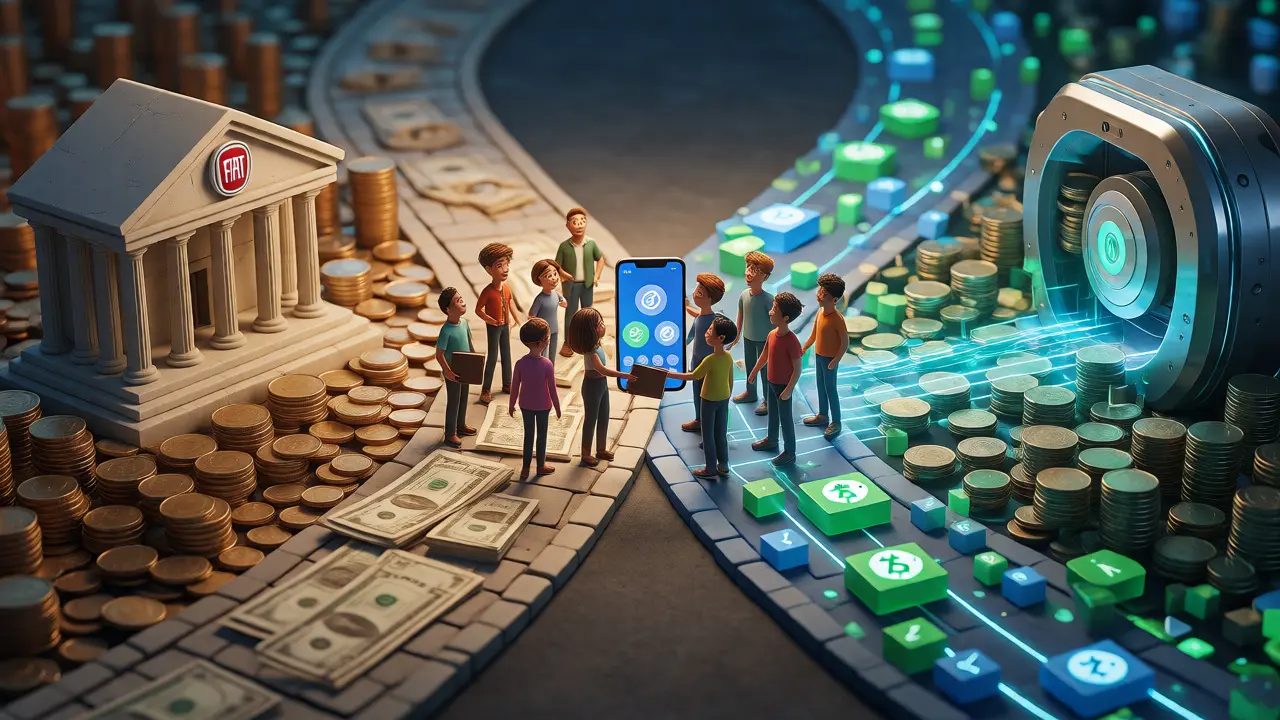
At its core, the difference between digital and fiat currency comes down to who controls the supply and how transactions are verified. One relies on government decree and central banks, while the other relies on code and community consensus. Understanding these mechanics helps you decide where to store your wealth and how to pay for things in an increasingly digital world. Let’s break down exactly what sets these two systems apart, without the confusing jargon.
What Is Fiat Currency?
Fiat currency is money that has value because a government says it does. It’s not backed by physical commodities like gold or silver. Instead, its worth rests on the "full faith and credit" of the issuing authority, such as the Federal Reserve in the US or the European Central Bank in Europe. You likely use fiat every day when you spend dollars, euros, or yen.
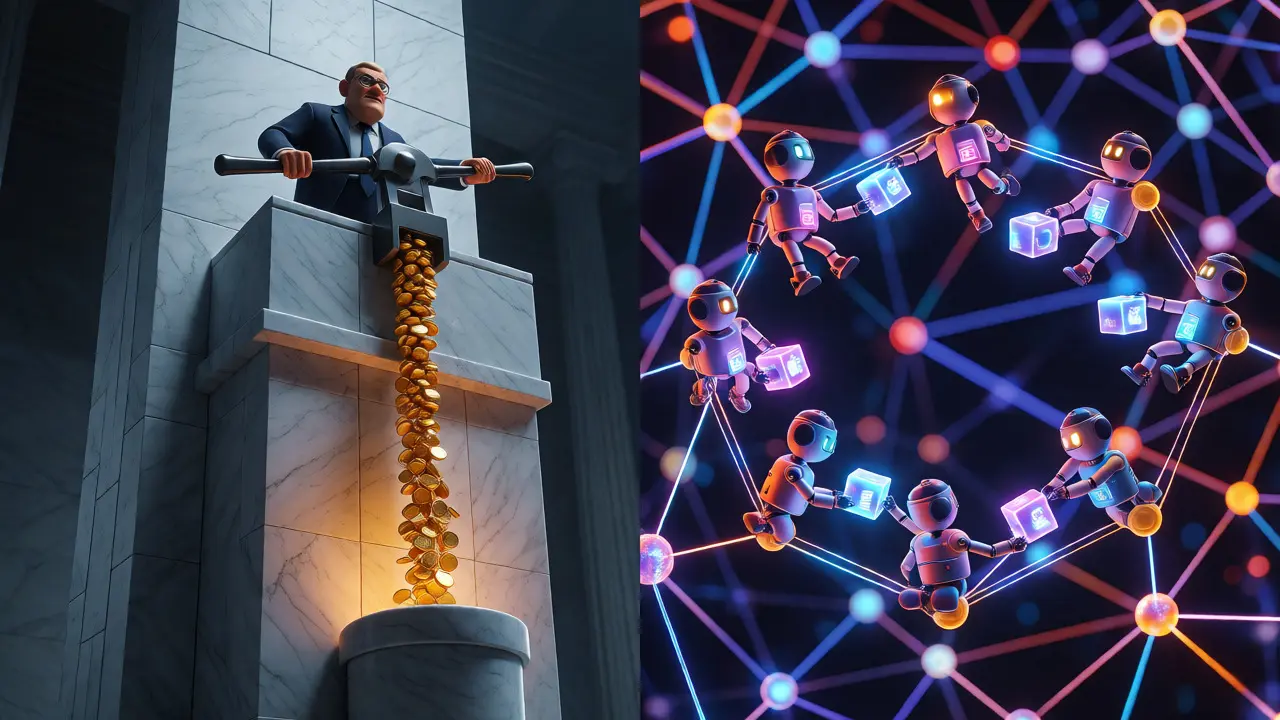
This system is centralized. A single entity, usually a central bank, controls the money supply. They can print more bills or adjust interest rates to manage inflation and economic growth. While this allows governments to respond quickly to crises, it also means they can devalue the currency by printing too much. Remember Zimbabwe? Or look at recent inflation spikes in major economies. When the supply grows faster than the economy, your purchasing power drops.
Fiat exists in both physical forms (coins and notes) and digital forms (bank balances). However, even digital fiat transactions rely on intermediaries. When you send money via a bank transfer or credit card, companies like Visa, PayPal, or Western Union process the transaction. These middlemen add layers of security but also introduce fees and delays, especially for international transfers.
What Is Digital Currency?
Digital currency is a broad term for any money that exists only in electronic form. While this includes digital versions of fiat (like your online banking balance), most people use the term to refer to cryptocurrencies like Bitcoin or Ethereum. These are decentralized assets secured by cryptography and recorded on a public ledger called a blockchain.
Unlike fiat, most cryptocurrencies have a fixed supply cap built into their code. Bitcoin, for instance, will never exceed 21 million coins. This scarcity is designed to prevent the kind of inflation seen in fiat systems. There is no central bank to print more Bitcoin if prices drop. Instead, new coins are created through a process called mining or staking, which validates transactions and secures the network.
Cryptocurrencies operate on peer-to-peer networks. When you send Bitcoin to a friend, you don’t need a bank to approve it. The transaction is broadcast to the network, verified by computers (miners or validators), and added to the blockchain. This process is transparent-anyone can view the transaction history-and immutable, meaning once confirmed, it cannot be changed or reversed.
Centralization vs. Decentralization
The biggest philosophical and operational divide between these two systems is control. Fiat currency is top-down. Governments set rules, central banks manage supply, and regulators oversee financial institutions. This structure provides stability and legal recourse. If your bank makes a mistake, consumer protection laws help you get your money back. If a business goes bankrupt, deposit insurance (like FDIC in the US) protects up to $250,000 per depositor.
Digital currencies, particularly cryptocurrencies, are bottom-up. No single entity controls the network. Changes to the protocol require consensus among participants. This decentralization offers censorship resistance-governments can’t easily freeze your crypto assets-but it removes safety nets. If you lose your private key, your funds are gone forever. There’s no customer service number to call. This "trustless" nature shifts responsibility entirely onto the user.
Trust mechanisms differ sharply here. Fiat relies on institutional trust: do you believe the government will maintain the dollar’s value? Crypto relies on mathematical trust: do you believe the code works as written? For many, math feels more reliable than politics, especially in countries with unstable governments.
Transaction Speed and Cost
If you’re sending money across borders, fiat can be slow and expensive. Traditional wire transfers often take several business days and involve multiple intermediary banks, each taking a cut. Credit card processing fees typically range from 1.5% to 3% for merchants, costs that are often passed on to consumers.
Cryptocurrency transactions vary widely depending on the network. Bitcoin transactions might take 10 minutes to an hour, while newer networks like Solana or Ethereum Layer-2 solutions can settle in seconds. Fees fluctuate based on network congestion. During high demand, Bitcoin fees can spike to tens of dollars, making small purchases impractical. However, for large international transfers, crypto can still be cheaper and faster than traditional banking rails.
| Feature | Fiat Currency | Cryptocurrency |
|---|---|---|
| Control | Centralized (Government/Central Bank) | Decentralized (Network Participants) |
| Supply | Unlimited (Can be printed) | Fixed or Algorithmic (e.g., 21M for Bitcoin) |
| Transparency | Limited (Bank records private) | Public Ledger (All transactions visible) |
| Volatility | Low (Stable for daily use) | High (Prices fluctuate rapidly) |
| Acceptance | Universal Legal Tender | Growing but Limited |
| Reversibility | Reversible (Chargebacks possible) | Irreversible (Final upon confirmation) |
Security and Privacy Risks
Security looks different in each world. Physical cash faces theft risks, but digital fiat benefits from established banking protocols. Fraud detection algorithms monitor suspicious activity, and regulations mandate identity verification (KYC). This reduces anonymity but increases accountability.
Cryptocurrency security depends on cryptographic keys. Your private key is like the password to your vault. If someone steals it, they own your money. Unlike banks, there’s no fraud dispute center for lost keys. However, the blockchain itself is highly secure against hacking due to its distributed nature. To alter the Bitcoin ledger, an attacker would need to control over 51% of the network’s computing power, which is prohibitively expensive.
Privacy is another trade-off. Fiat transactions are linked to your identity through bank accounts. Crypto transactions are pseudonymous-they show wallet addresses, not names. While this offers privacy, it’s not total anonymity. Sophisticated analysis can often link wallets to real-world identities, especially when interacting with regulated exchanges.
Regulation and Adoption
Adoption patterns show fiat dominating everyday commerce. You can buy groceries, pay rent, and file taxes in fiat almost anywhere. Legal tender laws require creditors to accept it. Cryptocurrency adoption is growing but remains niche for payments. Major companies like Tesla and Microsoft have accepted Bitcoin, but usage for daily purchases is still low compared to credit cards.
Regulatory frameworks are evolving rapidly. The EU’s Markets in Crypto-Assets (MiCA) regulation aims to provide clear rules for crypto firms. In the US, agencies like the SEC and CFTC are clarifying whether specific tokens are securities or commodities. This uncertainty affects institutional investment. Banks hesitate to hold crypto if the rules might change overnight.
Central Bank Digital Currencies (CBDCs) represent a hybrid future. China’s digital yuan and pilot programs in the US aim to combine fiat stability with digital efficiency. CBDCs remain centralized but offer faster settlement and programmability. They aren’t cryptocurrencies in the decentralized sense but signal that governments recognize the need for modernized money.
Which Should You Choose?
Neither system is inherently "better." They serve different purposes. Fiat excels at stability and widespread acceptance, making it ideal for paying bills and budgeting. Its predictability allows for long-term financial planning. Cryptocurrency offers innovation, potential appreciation, and borderless transferability. It serves well as a store of value (often called "digital gold") or for speculative investment.
Most experts suggest a balanced approach. Keep enough fiat for liquidity and daily expenses. Allocate a portion of your portfolio to digital assets for diversification. As technology matures, the lines may blur further. But for now, understanding the distinct roles of fiat currency and cryptocurrency empowers you to make smarter financial decisions.
Is digital currency the same as cryptocurrency?
Not exactly. Digital currency is any money that exists electronically, including your online bank balance. Cryptocurrency is a specific type of digital currency that uses encryption and decentralized networks like blockchain. All cryptocurrencies are digital currencies, but not all digital currencies are cryptocurrencies.
Why is fiat currency stable compared to crypto?
Fiat currencies are managed by central banks that adjust supply and interest rates to control inflation and stabilize value. Cryptocurrencies lack this central management, so their prices are driven purely by market supply and demand, leading to higher volatility.
Can I lose my money in cryptocurrency?
Yes. If you lose your private key or send funds to the wrong address, you cannot recover them. Unlike bank accounts, there is no central authority to reverse transactions or restore access. Market crashes can also significantly reduce the value of your holdings.
Are cryptocurrency transactions anonymous?
They are pseudonymous. Transactions are linked to wallet addresses, not directly to names. However, if you buy crypto with a bank account or use a KYC-compliant exchange, your identity can be traced to those addresses through analysis.
Will cryptocurrency replace fiat money?
It’s unlikely to fully replace fiat soon. Most experts predict coexistence, with fiat handling daily commerce and crypto serving specialized roles like cross-border payments or store of value. Central Bank Digital Currencies may also bridge the gap.
